
Reading at Advanced level
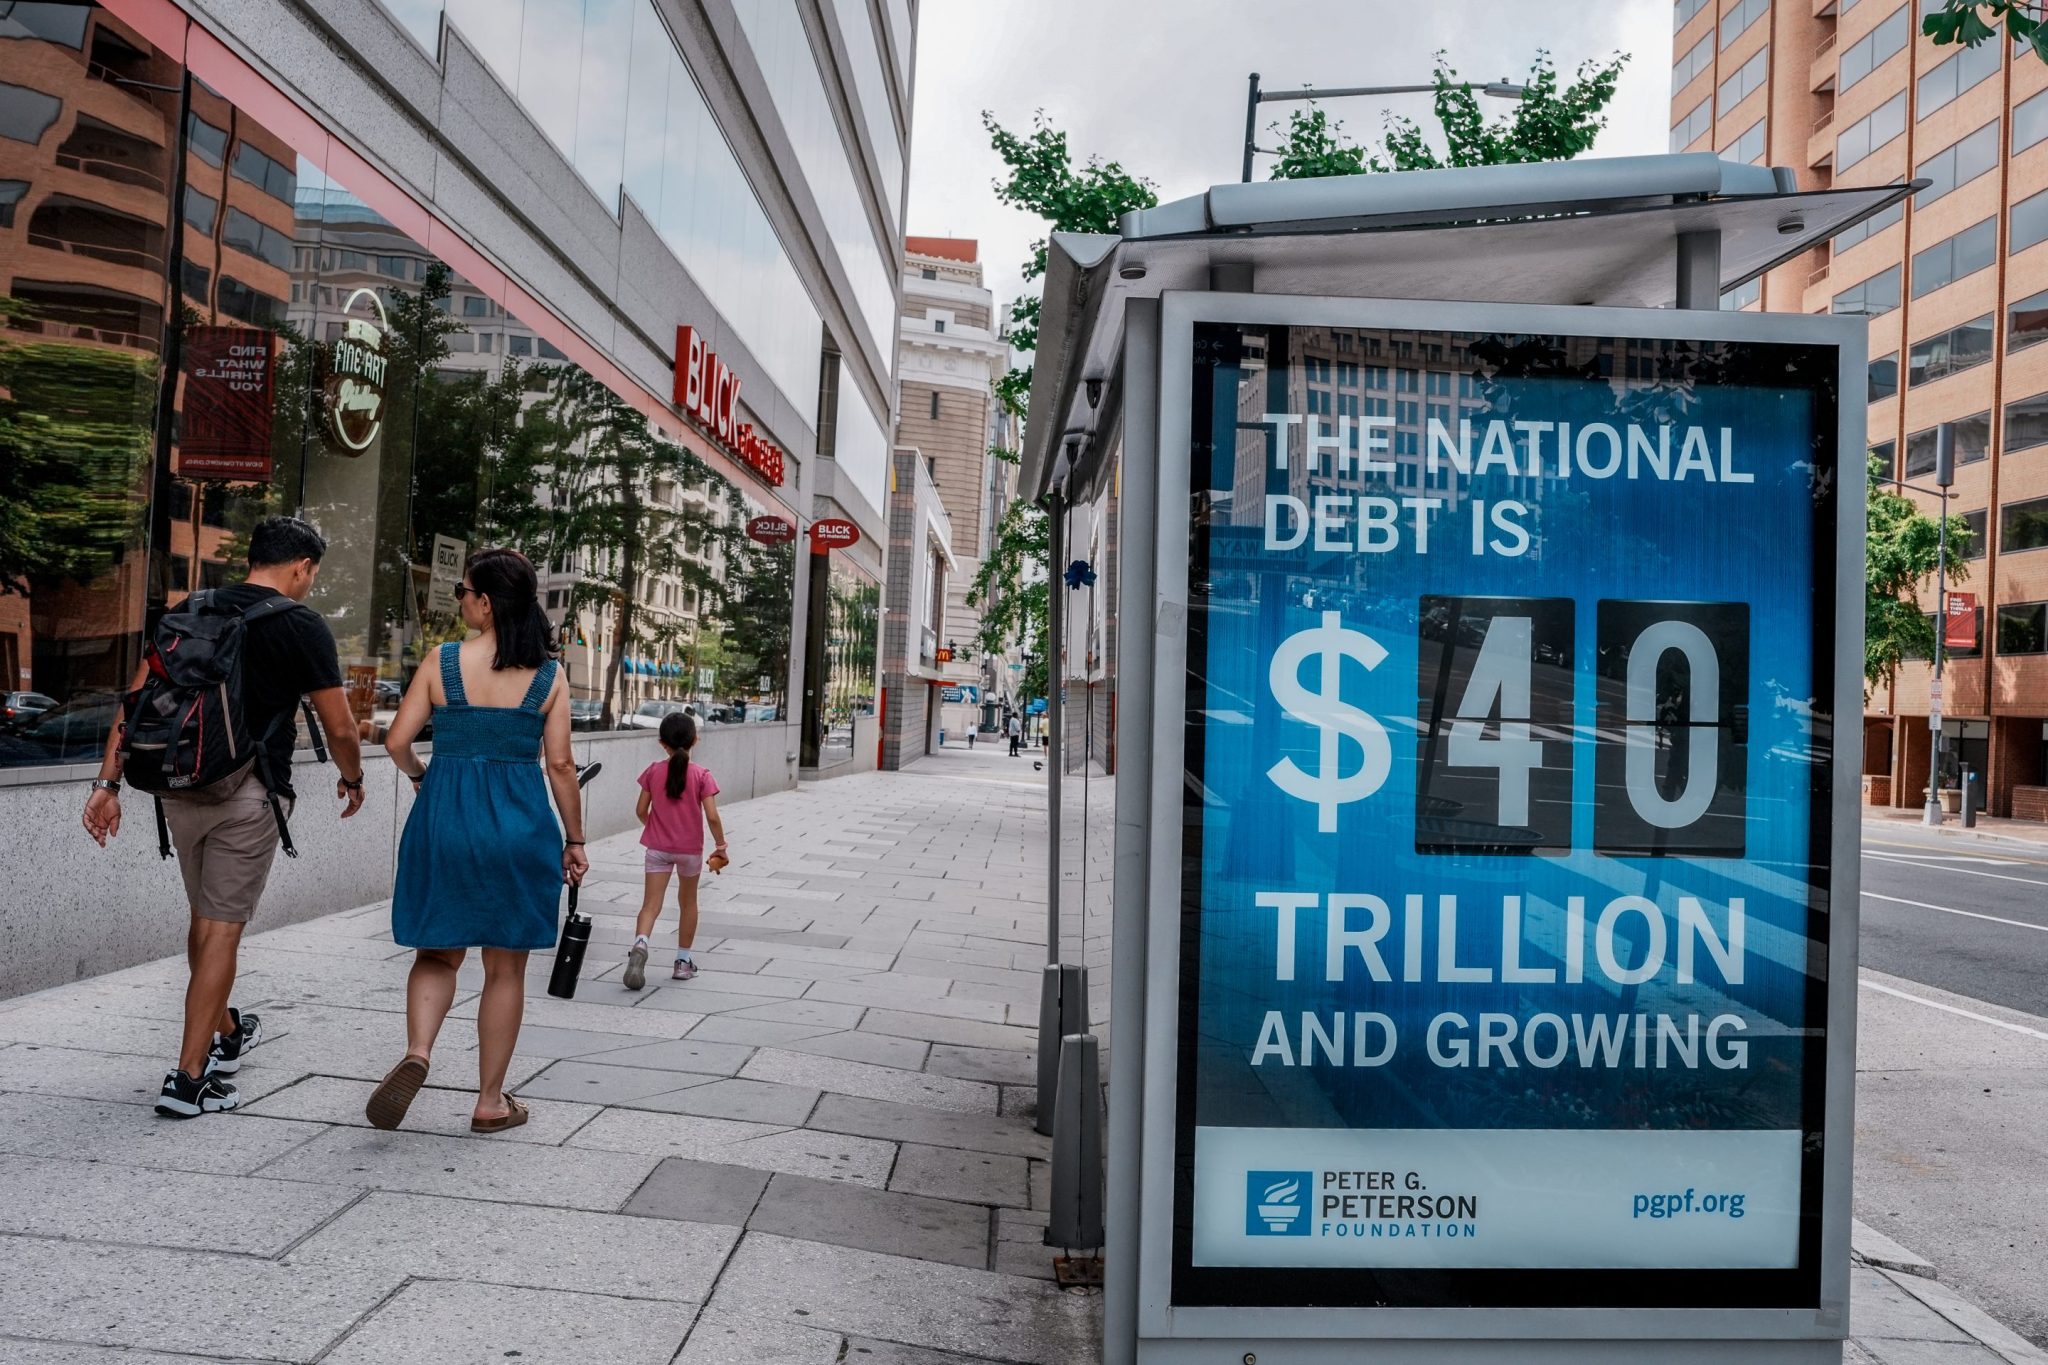
The 10-year Treasury yield has broken through the 5% barrier this week, marking a sustained climb since February and reaching the highest levels seen this cycle. The breach follows a Treasury Department-led buyback scheme intended to bolster market liquidity, yet yields resumed their upward trajectory ahead of the FOMC meeting as Middle Eastern geopolitical tensions and persistent inflation concerns reasserted downward pressure on bond valuations. At current levels, fiscal hawks warn of an acute debt dynamics problem: according to the Committee for a Responsible Federal Budget, should yields remain 80 basis points above current projections over the next decade, annual interest expenditure could reach $2.7 trillion by 2035—surpassing outlays for Medicare and Social Security combined. Such a trajectory would necessitate an accelerating debt-to-GDP ratio absent significant fiscal consolidation or nominal growth acceleration.
The broader macroeconomic transmission mechanisms remain contested. Critics contend that sustained 5%+ yields will meaningfully depress private investment through crowding-out effects, as firms face higher capital costs and households encounter elevated mortgage and consumer lending rates. Others emphasize that current yield dynamics may reflect rational expectations around potential growth and inflation rather than a flight from risk in U.S. Treasuries, and cite secular productivity gains from AI-driven technological advancement as a potential long-term escape valve. The geopolitical context complicates the narrative: rising yields are not confined to the U.S. market, with concurrent increases across major developed-market sovereigns pointing to shared structural pressures—higher oil prices, inflation expectations, and central bank policy expectations—rather than idiosyncratic fiscal deterioration. Treasury Secretary 'House' Bessent's recent market interventions have yielded limited efficacy, and market participants note diminished credibility in U.S. fiscal signaling.